Economic historian Robert Higgs makes some interesting observations at the Liberty & Power group blog. I often disagree with some of its foreign policy views – it verges on outright pacifism – but its economics I like.
|
|||||
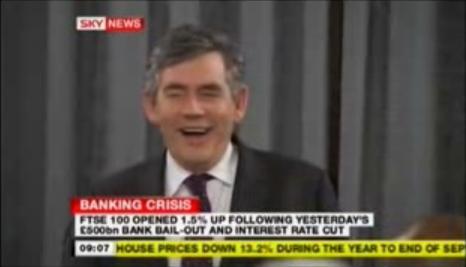 At least someone is enjoying themselves. The taxpayer has always paid his bills, except in his childhood, when God did. And now he gets to use unlimited power to seize whatever he likes and congratulate himself that he is punishing bad people for taking risks in the hope of making money for themselves. pic hat-tip: Guido October 10th, 2008 | 11 comments - (Comments are closed)
 This is a good, very fair-minded take on the current financial turmoil and all the more impressive for its insights precisely because the writer is not some sort of ultra-free market ideologue:
Absolutely. China, and the massive pool of savings that Asian economies have been able to provide to Western borrowers, is the 800 pound gorilla in the room in the current saga. The author continues:
Yep, Mr Greenspan has a lot to explain.
Try telling that to the likes of Will Hutton.
Quite. In recent years, I have often heard fellow libertarians say something on the lines that “we’ve won the economic argument but lost the cultural one” sort of thing. I have never been entirely convinced about that. Yes, old-style central planning and crushingly high tax rates are unlikely to make a comback, but never underestimate the age-old hatred of financiers, of speculators and great wealth. Those of us who might imagine that the big battle of ideas fought after the war against socialism have been won may want to shake off some complacency. But maybe I am being gloomy. After all, much of the current round of government “rescues” are not quite of the same order as the nationalisations of the past. And in some cases, we might hope that eventually states will return banks they have nationalised into private hands. As the French example of Credit Lyonnais shows – a corrupt bank if ever there was one – state-run banks are just as capable of making a mess of lending as any private one. October 8th, 2008 | 27 comments - (Comments are closed)
“Instead of thinking of the pending bailouts and financial regulation as a new era of government supervisions of markets, think of it as preserving the system in which a Harvard elite controls other people’s money. In fact, very little is likely to change. Reading the news stories about how Secretary Paulson plans to implement the bailout, it seems as though the same people will be in charge of the money. Print some new business cards, change the logo on the front from “Goldman Sachs” to “U.S. Treasury,” and everything else continues as it was. It’s just that it becomes a lot more difficult for ordinary people to opt out of using the elite’s money management services.” – Arnold Kling. He is not exactly a fan of the US financial bailout. October 7th, 2008 | Comments are closed
William Rees-Mogg wonders, in his Times (of London) column today, whether Barack Obama has it in him to be the next FDR. I sincerely hope not. Let us consider the following data on unemployment rates during the 1930s: 1930: 8.7% (Source: US Department of Commerce, Historical Statistics of the United States, as quoted by Thomas J. Lorenzo, in “How Capitalism Saved America, page 180-181), With a set of figures like that, perhaps it is no wonder that hagiographers of FDR prefer to focus more on his record as a war leader these days. If Obama does share any of FDR’s traits for sheer deviousness on the economic front, we have trouble on our hands. It is amazing how certain myths persist. Back in the early 1980s, when I was doing my history A-levels, one of my teachers gave me the whole ‘heroic’ portrait of FDR. I suspect this is still the default position of most history textbooks today. October 6th, 2008 | 43 comments - (Comments are closed)
Peter Mandelson’s re-appointment to Gordon Brown’s cabinet is a potential disaster, and not just for Britain. I have always liked Mandelson more than any other Labour politician. I ought to hate him, because his strategic genius gave us the New Labour revolution of the last decade. But his lucent unwillingness to pretend he is an imbecile, to conceal the fact of his cunning, or to act out his party’s customary hatred of private enterprise, even while his pupils execute their vile populist capers, is to me endearing. Maybe that is why I’m worried more than stunned by his return to British politics. While most commentators are mesmerised by the story of Brown’s feud with The Prince of Darkness, and the daring of playing with Labour Party’s own resentment of him by bringing him back from Brussels, I am more interested in strategy. Do not just look at the flashy sacrifice; see how it changes the board. There is now a gap in the European Commission. Brown will appoint one of his favourites to it, and have far reaching influence on Europe, and therefore Britain, even after he steps down. This can be seen as a subtle purge by bribery, and as a retirement strategy. A preparation for the Brown legacy. There is now a gap in the European Commission. Whoever fills Mandelson’s Trade portfolio will be replacing one of the most free-trade-friendly commissioners that the EU has ever had, in a financial crisis, with protectionist populism surging on both sides of the Atlantic. Brown’s legacy could easily be a trade war and a real depression. October 4th, 2008 | 16 comments - (Comments are closed)
From the Spectator:
This is from two weeks ago, so adjust for the financial turmoil since… the advice still stands. October 3rd, 2008 | 10 comments - (Comments are closed)
This is simply brilliant:
The serious point here, of course is that Americans are being asked to bail themselves out, or their more feckless citizens, many of whom are far richer than they. And this is meant to save “unregulated capitalism”, apparently. Thanks to Bob Bidinotto for the link. Bob has been on fire recently. October 2nd, 2008 | 9 comments - (Comments are closed)
Over at EU Referendum blog, there is a good item about the regulatory system which to a degree, lies at the heart of the current market turmoil. It refers to the network of rules known as Basel II, taking their name from the fact that the headquarters of the Bank of International Settlements is based in the Swiss city. BIS is the place that central bankers meet regularly to discuss regulations governing the world’s main banks and other financial institutions. I used to go to Switzerland quite a bit to sit in on some of the discussions surrounding these rules when I used to report on this sort of stuff. Essentially, the rules lay down how much capital banks should set aside to cover against risks. They are extremely complicated, but in a nutshell, they are designed to protect the financial system from a wave of debt defaults. The Basel II rules have in turn acted as the foundation for bank capital regulations in the EU and other major industrial economies. If I have a “point” to make here, it is that the existence of these and other regulations utterly nails the lie, put around by a lot of MSM commentators, that what we are seeing is the demise of unregulated, cowboy capitalism. Au contraire, what we have seen is the failure of a large body of rules, assembled over many years, to do what they were supposed to do. In fact, as EU Referendum persuasively argues, these rules may have even worsened the crisis and encouraged financial players to take certain risks “off balance sheet” to avoid having to set aside capital. But you can bet that policymakers will not draw the conclusion that too much regulation might actually be part of the problem. October 1st, 2008 | 21 comments - (Comments are closed)
Giving Bear Stearns Bank a bailout was vital – otherwise the financial system and the thing that unkind people call the “credit/money bubble”, would have collapsed. Bailing out Fannie Mae and Freddie Mac was also vital – otherwise the financial system would have collapsed. Senator Dodd and and Senator Obama were not paid a fortune by Fannie and Freddie for nothing. And bailing out AIG was vital to – otherwise, again, the financial system would have collapsed. And now all the “bad housing debt” of all the financial services companies must be taken up by the government – otherwise the financial system will collapse. And Paul Marks must be bailed out too. After all once one has spent a trillion Dollars, more Dollars than there are stars in the sky or cells in your hands, what is a few Dollars more? His judgements were no worse than that of the bankers and other such. In fact they were better – after all he did not take on a lot of housing loans without even knowing who the money had been loaned to or which people had a chance of paying the money back. And Paul Marks did not play complex games with the housing loans – treating a debt as an “asset” (“normal banking practice” of course) on which a vast castle-in-the-air could be built. The endless “lower interest rates” by the Federal Reserve system and the Bank of England, i.e. the endless flow of new credit/money that created the mad lending and manipulation in the first place, are not enough. Paul Marks must have a proper bailout – and he must have it now. If Paul Marks does not have a bailout I can assure you that the credit bubble financial system will come to grief. Of course a “bitter and cynical” person would say that the credit bubble financial system will come to grief even if Paul Marks gets his bail out. But that did not stop all the other bailouts. Each bailout was supposed to “save the financial system” and clearly did not, but that did not stop all the other bailouts. Now everyone is going to get a bailout, so Paul Marks must have one too! September 30th, 2008 | 35 comments - (Comments are closed)
The Cato Institute blog makes this observation:
I am not holding my breath. It would be interesting to see the reaction if she did give the bailout the finger, though. Judging by some of the media coverage of her and the credit crunch, large parts of the MSM press would lose their minds completely. September 30th, 2008 | 15 comments - (Comments are closed)
Watching the UK’s Channel 4 programme tonight, hosted by Jon Snow, whose leftist views are easily discernible, I sensed an aspect of the coverage of the present financial turmoil that bothered me. Several times, during various back-and-forth questions with such luminaries as the left wing journalist Will Hutton and the Cazenove economist Richard Jeffries (I know Richard, he is a smart guy), Snow came up with the idea that instruments such as financial derivatives were “peddled” by banks and other institutions to investors. You see, the viewer was supposed to understand, buying or selling a swap, or a future, an option, a warrant, or basket of bonds and equities is like buying or selling crack cocaine or a porno magazine, not that I have a problem with porn magazines. Of course, given the way in which hedge funds have been accused of colluding to destroy financial institutions such as Britain’s HBOS – which is beyond daft given that only a small fraction of HBOS shares were available to be short-sold in the first place – we can expect more of this demonisation of financial markets. Please understand me, gentle readers. I am not saying that banks and other intermediaries are not at times at fault for what has happened. Clearly it sticks in the throat to see bankers earn vast salaries in the good times and then bawl like so many 1980s coalminers or wheat farmers when the taxpayer refuses to get them out of trouble. I was grimly satisfied to see that the US allowed Lehman Brothers to go down, since it showed that at least some policymakers in the US were willing to see risk-takers pay the price of risks that have gone awry. But let there be no mistake: the financial derivative instruments that are being credited with voodoo powers by financial dunderheads like Will Hutton or Mr Snow are not the essence of the problem. Derivatives are, after all, borne out of the desire by people to offload risks and by the desire of others to take those risks on; they are a consequence of the different appetite for bearing risk that occurs in any open market economy. Some people like uncertainty, others do not. That difference explains how, in a world of price movement, it is possible for people to swap uncertainty for certainty and vice-versa. It is the basis of insurance, for example. Without speculators willing to bear risks of fluctuations in everything from wheat to interest rates, other, more timid souls would not have fixed-rate mortgages or upfront payments for their wheat. Without those hedge funds, other, more cautious investors would not get prices for their investments, and so on. We are in the midst of a very scary time in the financial world and there is no point in my trying to obscure that fact. I work in the wealth management business and have seen even some of the smartest minds in the business lose their heads. But I detect a decidedly unpleasant whiff in the air of scapegoating in the current time. One almost can hear an echo of anti-semitism, or something very similar. Meanwhile, Roger Kimball pins much of the blame on US policies designed to encourage risky borrowers to get credit. He has got a point. I would also repeat the point that with Japan and other Asian countries operating ultra-low interest rates for a long time, these countries acted like ATM machines for the rest of the world. As Paul Marks of this parish likes to point out, until interest rates are based on a genuine balance between the demand for and stock of savings, the monetary system of the world will keep creating bubbles like this. Update: here is a fine essay by economics historian Robert Higgs about how disastrous policy responses in the US ensured that the Wall Street Crash of 1929 mutated into a decade-long slump. Over and over again, it is necessary to nail the myth of Roosevelt’s New Deal. Far from “saving” US capitalism from itself, FDR lengthened the misery; unemployment was higher by the outbreak of WW2 than when he was elected to office. September 29th, 2008 | 26 comments - (Comments are closed)
|
   |
||||
All content on this website (including text, photographs, audio files, and any other original works), unless otherwise noted, is licensed under a Creative Commons License. |
|||||
Recent Comments